Published: September 11, 2026
Monrovia – The Law Reform Commission of Liberia (LRC) has called for urgent legal integration and targeted reforms to resolve Liberia’s persistent non-performing loans (NPLs) problem, warning that existing laws remain fragmented and insufficiently operational to support faster, cheaper, and more predictable loan recovery.
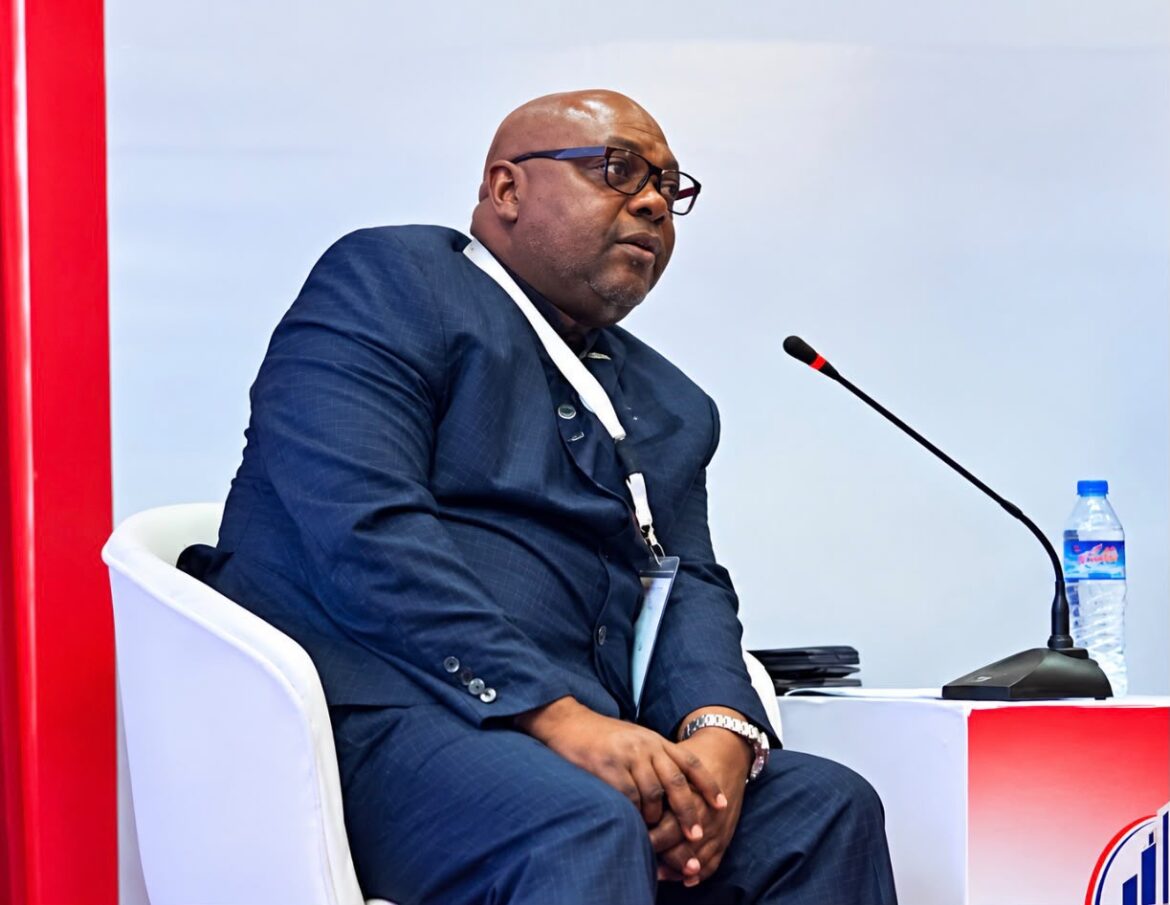
The three-day National NPL Resolution Conference, now in its second day at the Ellen Johnson Sirleaf Ministerial Complex in Congo Town, is organized by the Central Bank of Liberia under the World Bank-supported Liberia Investment Finance and Trade (LIFT) Project. The forum has convened several participants including regulators, commercial bank executives, judicial officials, lawmakers, and international partners from the World Bank, IMF, Bank of Ghana, and Central Bank of Egypt to address Liberia’s high NPL ratio and design reforms to restore credit growth.
In a panel discussion lead by Ex Finance Minister and director of West African monetary Agency Boima S. Kamara, on the “Legal and Regulatory Framework for Resolving Non-Performing Loans in Liberia,” LRC Chairperson and Chief Executive Officer, Cllr. Bornor M. Varmah, posed a fundamental question: Does Liberia have an adequate legal framework to resolve today’s NPLs, or must the law be reformed?
His deliberation entailed that “Liberia has important building blocks, but the framework is not yet sufficiently integrated, efficient or operational to deal with the scale and complexity of today’s NPL problem.”
Cllr. Varmah stressed that the issue is not the absence of laws, but the lack of a seamless NPL-resolution architecture. He cited the Commercial Code, the Insolvency and Restructuring Act of 2016, the Commercial Court framework, the Bank Financial Institutions Act, and the CBL’s prudential regulations as important foundations, but noted critical gaps across default, enforcement, restructuring, insolvency, collateral realization, and final recovery.
He identified five priority areas requiring attention. First, the Insolvency and Restructuring Act, which he said lacks the secondary rules needed to make restructuring a genuine alternative to liquidation. Second, the Commercial Code’s secured transactions provisions, where he noted that “the real test is enforcement after default.” Third, mortgage and real-property enforcement, which he said needs clearer, time-bound foreclosure procedures. Fourth, the Commercial Court, which needs specialized NPL procedures and expedited debt claims. Fifth, the banking-resolution framework, where operational regulations have taken longer than anticipated.
On secondary regulations, Varmah distinguished between rules already being enforced by the CBL — including full provisioning after one year and the 10-percent NPL threshold — and outstanding bank-resolution instruments. He questioned whether the bank-resolution regulations, operational guidelines, Resolution Manual, and remedial framework for weak banks have been formally adopted, published, and made operational.
To move forward, the LRC proposed a three-track legal reform agenda: immediate administrative action to operationalize existing regulations without waiting for the Legislature; targeted legislative amendments through a clause-by-clause audit of key laws; and ultimately, a unified NPL resolution architecture where default to closure operates as one coherent legal process rather than separate legal islands.
”We do not need to begin from zero,” Varmah concluded. “What we need now is legal integration, institutional coordination and implementation.”
He pledged the Commission’s readiness to work with the CBL, Judiciary, Ministry of Finance, Liberia Bankers Association, and development partners to undertake a targeted NPL Legal Reform Audit, declaring: “A loan should not become a permanent legal dispute merely because it has become a non-performing asset. Collateral should represent realizable value, not merely value written on a bank’s balance sheet.”
See more Liberia News Network stories in Google Search by adding LNN as one of your Preferred Sources.
★ Add LNN as a Preferred Source